Build a Lasting Business Growth Strategy in the UK for 2026
For many smaller firms, costs remain a top concern, with 39% of SMEs reporting difficulties in obtaining finance. This is the challenging climate many owner-managers face in 2026. You want to grow, but cash flow, margins, and funding conditions often hold you back.
You didn't build your company to stand still. You want stronger profits, a clearer path for the next generation, and the freedom to choose when you step back. A clear business growth strategy in the UK can protect working capital, reduce risk, and keep family outcomes on track.
Why unplanned expansion puts strain on the business you have built
Ambition isn't the problem; the real challenge is expanding before you fully understand what the numbers can sustain. Higher costs, weaker margins, and uneven cash flow can quickly make a promising opportunity feel unsafe. New staff, additional premises, and extra services all look appealing until a late payment or a tax bill arrives at precisely the wrong moment.
This hits owner-managed firms especially hard because you carry both the commercial risk and the family wealth behind the company. In sectors like healthcare, childcare, care, professional services, or property, income timing and regulation can make cash even tighter. A durable plan links opportunity with forecasting, funding, and risk, ensuring growth protects what you’ve already created.
A practical business growth strategy for UK owner-managers
Sustainable growth isn't just about winning more work; it's an integrated business strategy that aligns your accounts, tax, funding, and personal family goals, helping you unlock business potential without putting your company or estate under pressure.
1. Start with a clear financial baseline
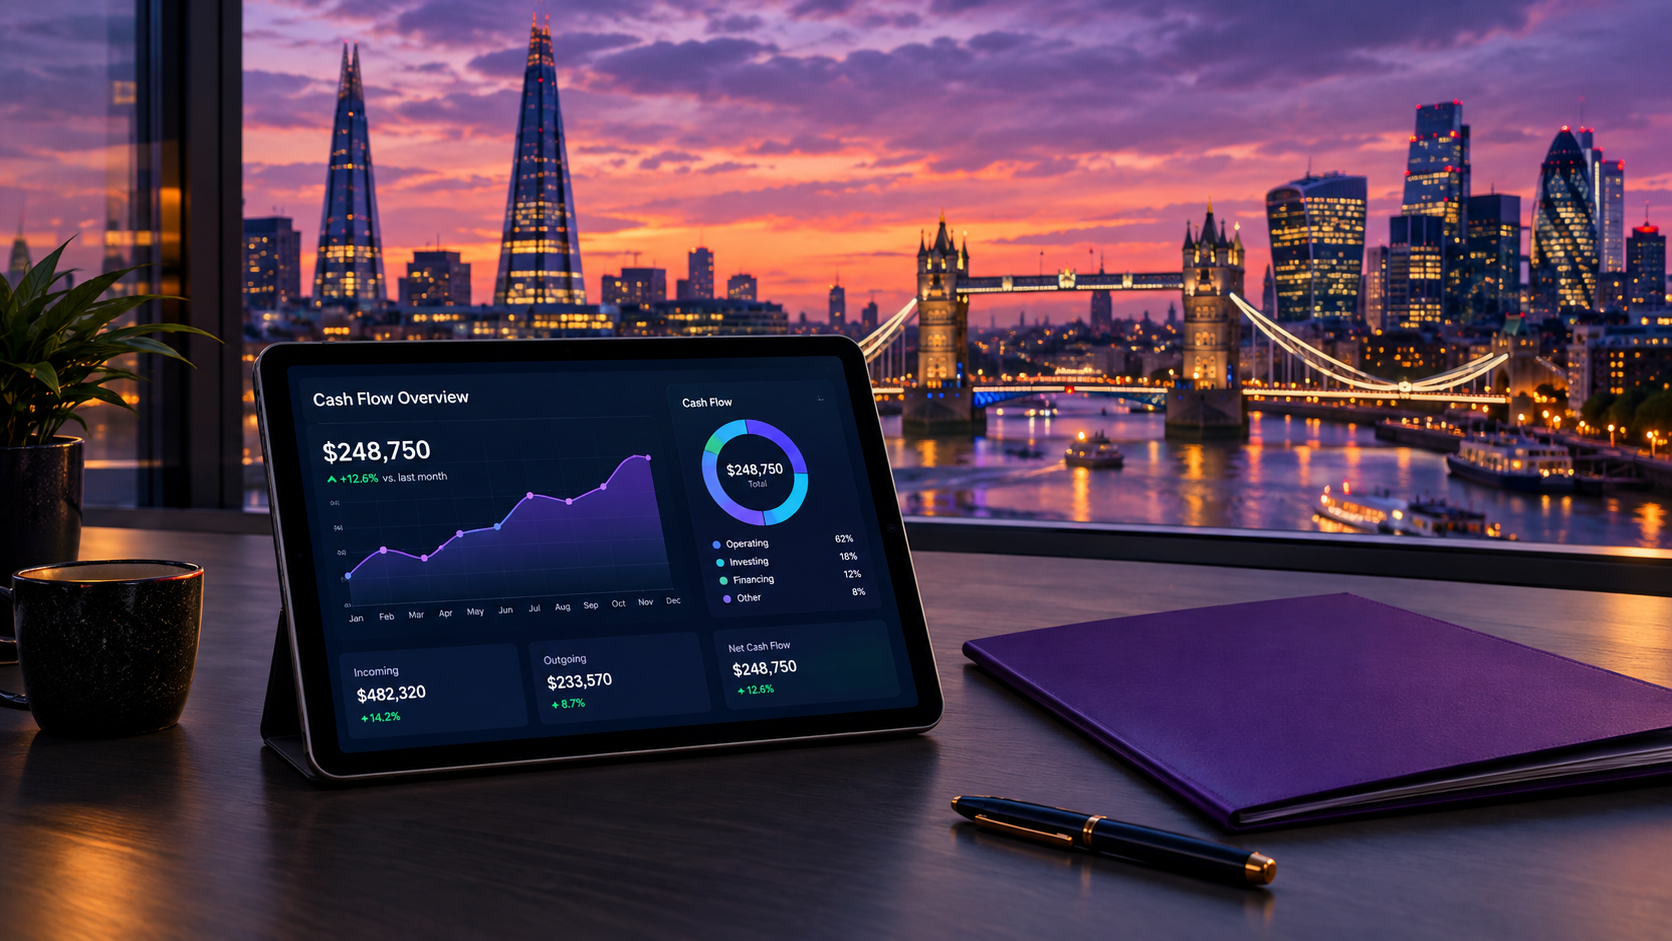
Before you hire, open another site, or launch a new service, you need a true picture of profit, cash, and tax . Look closely at your margin by service, how long customers take to pay, tax timing, and the cash buffer you truly need. Strong management information forms the foundation of effective owner-manager advisory that drives real change.
We recommend using a 13-week cash forecast alongside a 12-month profit view, updated every month. If you can't confidently explain where your cash will be in 90 days, you're simply not ready to scale.
2. Rank opportunities instead of chasing every idea
List the options in front of you: deeper sales to current clients, a new location, a new service, or an acquisition. Score each one on margin, cash required, people risk, regulation, and time to payback. SME growth consulting is most useful when it helps you say no to work that looks busy but weakens cash.
A practical tactic is to set a simple rule: only pursue ideas that maintain a cash buffer equal to three months of overheads. Write this down and share it with your leadership team.
3. Test the plan under pressure
Strategic business planning should include more than a best-case spreadsheet. Run a base case, a delayed-sales case, and a higher-cost case. Ask what happens if staff costs rise, a major client pays 30 days later, or borrowing costs increase. If the plan only works in perfect conditions, it's not ready.
For this, consider developing three scenarios: one with your base growth target, and others with delayed sales and higher costs, each showing different cash outcomes. Decide in advance which numbers would trigger a pause in hiring.
4. Get finance-ready before you need the money
Investors have been selective about equity funding for smaller UK businesses. The British Business Bank, in its Small Business Equity Tracker 2025, reported that smaller-business equity funding fell and deal numbers dropped.
London still attracts a large share of UK equity investment, which creates opportunity and competition for ambitious firms across Greater London.
Corporate finance advice helps you choose the right funding route, whether it's an overdraft, term loan, asset finance, or equity. Lenders and investors want credible forecasts, a clear use of funds, and evidence that you can meet the commitment. Preparing your pack before you approach anyone ensures you negotiate from strength, not urgency.
A smart tactic is to write a one-page note outlining how you will use the money, maintain 24 months of forecasts, and prepare a simple valuation story if you're considering investors. This comprehensive pack ensures you can move quickly when the right facility becomes available.
5. Join growth to tax, succession and family wealth
Expansion changes your personal picture, because higher profits can raise tax and new shareholders or a second generation joining the board can affect control. Property, pensions and eventual probate all sit in the same story. We help you look at the full picture , not only the year-end accounts.
If you're planning a sale, a gift of shares, or a move towards retirement, connect your growth plan to taxation and estate planning early to ensure more of the value you create stays within the family, and integrate probate support with your commercial plan from the outset, rather than as an afterthought.
6. Review monthly and decide quarterly
A plan that sits in a drawer doesn't protect you. Meet monthly on cash and margin. Decide quarterly which growth bets to keep, pause, or stop. This rhythm gives you control without drowning you in reports.
What this looks like in practice
As one director, AH, shared: "Pricemann and team have helped me to transform my business and finances over the years leading me to the position of making some of our dreams come true." This perfectly illustrates the value of joined-up advice, where your numbers and family goals move forward together.
Puja Kohli, another valued client, praises, "Shaileen is our go to guy for any accounting or business advise. Thank you Price Mann." We believe you need a trusted partner who understands both the accounts and the deeper story behind them, especially if you've built significant wealth as a first- or second-generation East African family.
If you run a growing firm in UK, the same discipline applies. Local opportunity is real, but growth that looks exciting on paper still has to fund itself in cash.
Key takeaways you can act on in 2026
- Treat growth as a financial decision, not only a sales target.
- Protect cash first, then scale the work that earns the best margin.
- Prepare funding evidence before you need it.
- Align expansion with tax, succession and the wealth you want to pass on.
- Use a simple monthly and quarterly rhythm so the plan stays alive.
Ready to turn growth into a clear plan?
We combine accounting, tax, and consulting to empower you to expand with confidence, not guesswork. Bring us the full picture of your business and your family, and we'll help you shape a plan you can truly fund and follow. If you're looking for a partner who understands both the numbers and the story behind them, Speak to a specialist today.